Yes, cautiously — it's a show-me buy.
Thesis
Bull case
The US miss was self-inflicted execution (weak promo marketing, digital-deal pullback), which management can fix — and the Sept 8 Extra Value Meals relaunch plus restored digital offers are immediate levers. BK's +8.5% comp proves the consumer is there. International (>50% of profit) is comping positively, systemwide sales +5%, FY26 EPS still growing ~8% with net-positive revisions, beverages are early traction, and ~$7.5B/yr of buybacks+dividends supports the floor. At ~19.8x forward and 2.9% yield, stabilization at Q3 (late Oct) triggers multiple mean-reversion to 22-23x = ~$285-300, ~12-17% plus yield in 3-6 months.
Bear case
Two years of value-platform spending (including franchisee subsidies) hasn't restored traffic, value perception among low-income consumers has weakened since July 2025, and Reuters reports cheap deals are losing effectiveness industry-wide — this may be structural demand erosion, not execution. MCD is actively losing share to a better-executing BK. FY2027 estimate cuts (3 up/25 down) are likely just beginning if traffic doesn't inflect, beef inflation squeezes franchisee economics, and GLP-1 adoption (~8% fast-food spend cut per user household, accelerating with oral pills) is a compounding headwind with no offset. A 'cheap' multiple on falling estimates is a value trap: if FY27 EPS slides toward ~$13.00, even 19x forward is ~$247 — below the current price.
What would change our mind
- Q3 2026 US comps flat-to-negative or another material miss vs. peers at the late-October print
- FY2027 consensus EPS falls below ~$13.50 (from $13.93) — signals the growth algorithm is breaking, not just traffic noise
- Management cuts or further delays unit-growth/margin targets, or signals franchisee distress
- Evidence that GLP-1-driven demand loss, not execution, is the dominant driver of US traffic weakness
- Stock breaks decisively below ~$240 on deteriorating fundamentals (not market-wide selloff), indicating the yield floor isn't holding
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The price embeds failure of the two-year value platform: ~19.8x forward earnings and 2.9% yield for a business that historically commands mid-20s trailing multiples. Consensus targets ($315-325 avg) imply ~25% upside, but targets were set before the latest slide and are drifting down; FY2027 EPS revisions are net-negative (3 up / 25 down over 30 days, cut $0.10 to ~$13.93), signaling the market doubts the ~8% 2027 growth baked into estimates. Effectively, the market prices MCD as a no-growth yield vehicle until US guest counts prove otherwise.
Why the market may be wrong
The market may be over-extrapolating a self-inflicted execution problem. Management attributed ~two-thirds of the traffic shortfall to lost visits from loyal customers driven by weak promo execution and a digital-deal pullback (Reuters, Aug 4 2026) — operational mistakes, not demand destruction. International (>half of systemwide sales and operating profit) comped +1.5% with strength in Germany, Australia, UK, and systemwide sales grew 5%. The BK +8.5% comp proves the low-income consumer is still spending on QSR — traffic is winnable, and MCD's miss reads as fixable share loss rather than category decline. If that's right, consensus is pricing a structural problem that is actually operational.
The one thing to watch
The de-rating is entirely about 2027 credibility, not 2026 reality: FY2026 EPS revisions are still net-positive (+14/-13) while FY2027 revisions are bleeding (3 up/25 down) — so the single variable to watch is not comps per se but whether the FY27 estimate bleed stops after the Q3 print. If Q3 US comps stabilize around +1-2% and FY27 estimates hold near $13.90 while the stock stays at 52-week lows, that is pure multiple compression with intact earnings — the cleanest mean-reversion setup. Note: a TD Cowen claim of 'no traffic improvement after the Sept 8 relaunch' is date-inconsistent with today (Sept 6) — treat it as garbled; the relaunch is an untested catalyst, not a failed one.
Key evidence (9)
- Q2 2026 (reported Aug 4, 2026): adj EPS $3.38 beat vs $3.32 consensus; revenue ~$7.1B slightly below $7.14B est; US comps +0.8% vs Burger King +8.5%; global comps +1.3% [T2 Reuters; company release]
- FY2025 SEC XBRL: revenue $26.885B, net income $8.563B, diluted EPS $11.95, operating margin 46.1% (best of 2021-2025) [T1 SEC]
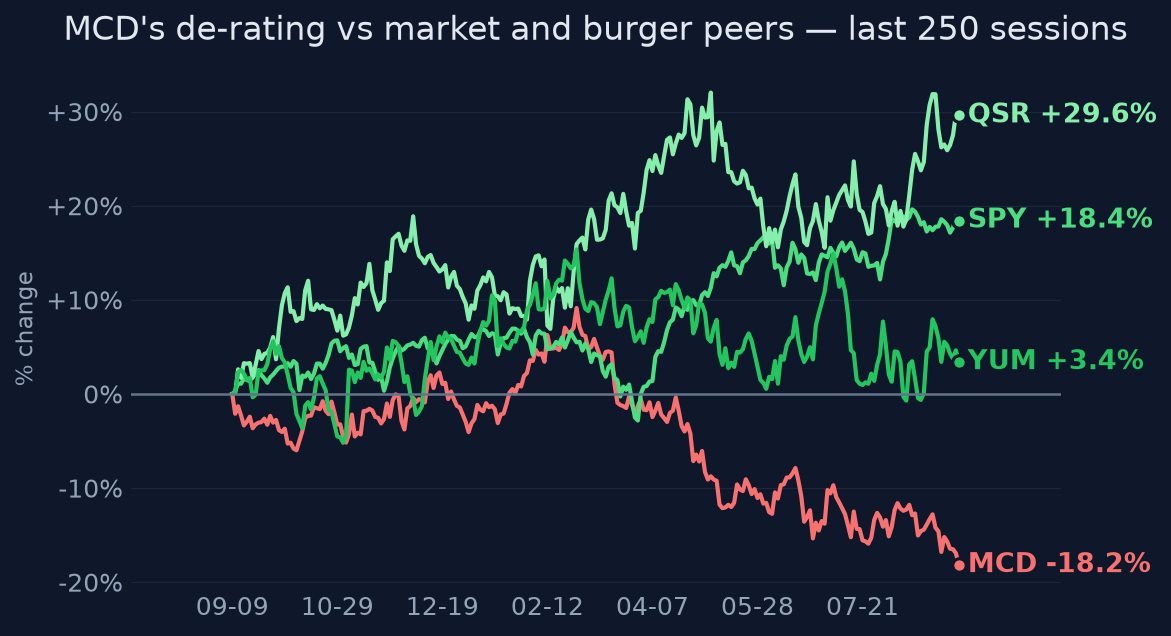
- Price/technicals as of 2026-09-04: $255.69, 52-week low, -25% below high, -19.3% 1y vs SPY +18.7%; RSI 35; idiosyncratic underperformance (QSR +29.1% 1y, YUM +4.9%, DPZ -26.3%)
- Valuation: trailing P/E ~21x vs 3-yr avg ~25x and 10-yr mean ~26.5x; forward P/E ~18.6-19.8x; dividend $7.44 annualized = ~2.9% yield [T4 ycharts/stockanalysis/Yahoo — valuation and target data rest on T4 sources, not independently verified against T1/T2]
- Revisions (Zacks, Aug 19, 2026): FY26 EPS raised $0.02 to $12.88 over 30 days; FY27 cut $0.10 to $13.93; FY27 revisions 3 up / 25 down [T4]
- Reuters (Aug 11, 2026): value deals 'no longer do the trick' industry-wide; low-income consumers squeezed by gas/goods costs [T2]
- GLP-1: Reuters-cited research shows GLP-1 households cut fast-food spend ~8%; oral pill approval accelerating adoption (Reuters Dec 2025/Feb 2026) [T2]
- Capital returns: ~$2.3B buybacks + $5.2B dividends TTM to June 30, 2026 [T4]
- Analyst targets: avg $315-325 (range $250-$407); TD Cowen and Bernstein cut targets post-Q2; 50,000-restaurant target pushed to 2028 [T4]
Catalysts and risks
Catalysts
- Sept 8, 2026 Extra Value Meals relaunch in the US — first test of fixed promo execution
- Q3 2026 earnings, expected late October 2026 — the decisive US traffic/print test
- Weekly/monthly third-party US traffic and credit-card data between now and the print
- Potential management updates on franchisee economics and beverage platform expansion
- Any 2027 guidance framing at year-end; analyst revision direction through September-October
Risks
- FY2027 EPS revision bleed accelerates (currently 3 up / 25 down over 30 days), making the forward multiple optically cheap on falling estimates
- US traffic fails to respond to the relaunch — confirming structural demand loss or permanent share cession to BK
- GLP-1 adoption compounds the low-frequency-customer problem with no management offset
- Beef cost inflation compresses franchisee profitability, forcing more corporate subsidies that hit margins
- Franchisee-level economics are unverified in this research — a hidden stress point
- Analyst targets ($315-325) are stale and drifting down; the 'implied upside' is partly an anchoring artifact
What to watch
- FY2027 EPS revision ratio over the next 30-60 days — stabilization of estimates matters more than the comp print itself
- US comp traffic component (guest counts, not just check/mix) at Q3 — vs BK's trajectory
- Initial reads on the Sept 8 Extra Value Meals relaunch (third-party traffic data, franchisee commentary)
- Digital deal intensity restoration — management flagged its pullback as a key driver of the miss
- Beef price trends and any disclosure on value-meal subsidy burden
- Whether the stock holds the 52-week-low zone (~$250-256) into the print — a break before Q3 would signal informed selling
Market snapshot when the call was made 2026-09-04
Price
| Return 1w | -3.5% |
| Return 1m | -7.5% |
| Return 3m | -8.6% |
| Return 6m | -22.1% |
| Return 1y | -19.3% |
| From 52-week high | -25.0% |
| Realized vol, 20d | 18.4% |
| SPY 3m / 1y | +4.4% / +18.6% |
| QQQ 3m / 1y | +2.0% / +25.0% |
Technicals
MCD technicals as of 2026-09-04: last close $255.69; 20d SMA 267.11 (neutral); 50d SMA 269.47; 12d EMA 263.12; 26d EMA 266.33; RSI 14 35.4 (balanced); 20d vol 18.2%; volume x1.0 vs 20d avg
Verifier notes PASS
Weakly sourced
- Burger King's +8.5% US comp — a load-bearing figure for the 'traffic is winnable / fixable share loss' thesis. Within the bundle its explicit source is thestreet.com [T4]; the opinion tags it [T2 Reuters] in key_evidence, but no retrieved Reuters answer text in the bundle actually states the 8.5% figure. The tag overstates the sourcing quality, though the planner digest made the same attribution, so this is inherited rather than fabricated.
- 'Value perception among lower-income consumers has weakened since July 2025' (bear case) — rests solely on the TD Cowen note via investing.com [T4], stated as fact without attribution in the bear case.
- Analyst target range ($250-$407, avg $315-325) and capital-return figures ($2.3B buybacks / $5.2B dividends) are T4-only — though the opinion explicitly acknowledges this in key_evidence, which mitigates the issue.
Corrections applied
- Optional, non-blocking: re-tag the BK +8.5% comp as [T4] or note it is secondhand via Reuters-reported coverage rather than directly verified against a Reuters article.
- Optional, non-blocking: attribute the 'value perception weakened since July 2025' claim to TD Cowen in the bear case rather than stating it baldly.
Sources (26 · T1 = primary filings)
- T2https://www.reuters.com/business/mcdonalds-us-sales-disappoint-value-deals-fail-draw-enough-diners-2026-08-04/
- T4https://www.investing.com/news/analyst-ratings/td-cowen-lowers-mcdonalds-stock-price-target-on-weak-us-sales-9…
- T2https://www.reuters.com/business/mcdonalds-rivals-cheap-deals-no-longer-do-trick-2026-08-11/
- T4https://moneycheck.com/mcdonalds-mcd-stock-tumbles-to-multi-year-lows-amid-sales-struggles-in-2026/
- T4https://finance.yahoo.com/markets/stocks/articles/mcdonalds-stock-down-19-6-160700198.html
- T4https://corporate.mcdonalds.com/corpmcd/investors/financial-information.html
- T4https://ca.investing.com/news/stock-market-news/bernstein-cuts-mcdonalds-stock-price-target-on-delayed-growth-…
- T4https://finance.yahoo.com/markets/stocks/articles/mcdonald-keeps-cratering-why-one-114239056.html
- T2https://www.reuters.com/business/mcdonalds-launch-3-value-meals-us-starting-april-wsj-reports-2026-03-11/
- T4https://corporate.mcdonalds.com/corpmcd/investors.html
- T4https://www.thestreet.com/investing/stocks/burger-king-passes-wendys-restaurant-brands-earnings-qsr
- T4https://corporate.mcdonalds.com/corpmcd/investors/financial-information.%E2%80%8Chtml.html
- T2https://www.reuters.com/business/retail-consumer/us-shoppers-tighten-budgets-still-find-room-treats-splurges-2…
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/weight-loss-pill-approval-set-accelerate-food-indu…
- T2https://www.reuters.com/legal/litigation/big-food-pours-millions-into-rebrands-obesity-drugs-reshape-us-demand…
- T4https://quartr.com/companies/mcdonald-s-corporation_5595
- T4https://www.stockinsights.ai/us/MCD/earnings-transcript/fy23-q4-0e76
- T4https://finance.yahoo.com/quote/MDO.DU/earnings/MDO.DU-Q4-2025-earnings_call-409960.html
- T4https://public.com/stocks/mcd/pe-ratio
- T4https://finance.yahoo.com/quote/MCD/
- T4https://stockanalysis.com/stocks/mcd/
- T4https://www.marketbeat.com/instant-alerts/research-analysts-issue-forecasts-for-mcdonalds-q3-earnings-2026-08-…
- T4https://ycharts.com/companies/MCD/pe_ratio
- T4https://tickerleague.com/companies/MCD/financials/pe-ratio
- T4https://simplywall.st/stocks/us/consumer-services/nyse-mcd/mcdonalds/dividend
- T4https://companiesmarketcap.com/mcdonald/pe-ratio/
Earlier and later calls on MCD
- Oct 20, 2026Momentum trap — timing trap, not value trap.Lean bearishview changed
- Oct 9, 2026Cheap, but not yet cleared.Lean bullish
- Oct 6, 2026Oversold reset — cautiously attractive.Lean bullish
- Oct 6, 2026Oversold derating — lean bullish into Q3.Lean bullish
- Sep 23, 2026Dipped, yes. Undervalued, probably.Lean bullish
- Sep 23, 2026Washed out, not broken — lean bullish.Lean bullish
Want a fresh look at MCD, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 6, 2026. Not personalised advice. Figures use end-of-day closes.